SL Green and Mori Trust lined up a $2bn CMBS refinancing for New York's 245 Park Avenue. A CMBS loan is one a lender bundles with other loans and sells to bond investors. Landing one this size shows bond buyers still want to fund a top Manhattan office tower. PERE
Why it matters: a clean refinancing on a trophy tower gives owners of lesser buildings a benchmark, but one only the best assets may reach.
GlobeSt reports that office CMBS lending is spreading beyond trophy towers to more ordinary buildings. For two years lenders stuck to the safest, highest-quality offices. A wider appetite means more owners can refinance maturing debt. GlobeSt.com
Why it matters: if lenders fund more than just the best offices, owners of mid-tier buildings have a better shot at refinancing instead of defaulting.
The CREFC sentiment index, a survey of commercial real estate finance pros, fell 17.5% to a three-year low. The drop signals that lenders and investors feel worse about the months ahead. CRE Daily
Why it matters: when the people who make loans turn gloomy, credit gets tighter and pricier for every borrower.
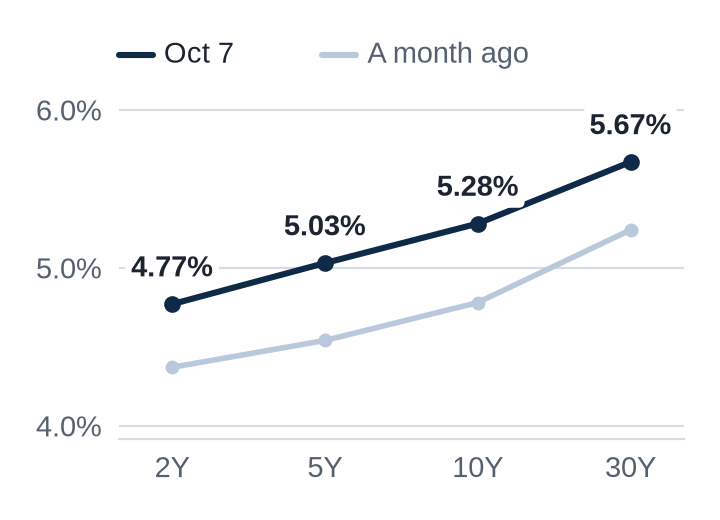
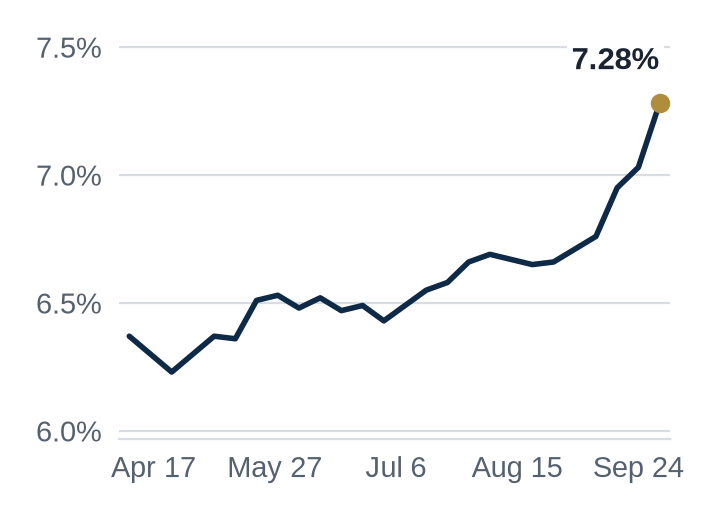
A bridge loan is short-term debt that an owner takes while arranging permanent financing. Owners facing maturing loans are stacking one bridge loan onto another to postpone a sale or refinancing they cannot afford today. The bet buys time, but it gets riskier as borrowing costs climb. Bisnow
Why it matters: Owners delaying a reckoning keep troubled properties off the market, so lenders and buyers waiting for cheap distressed deals may keep waiting, while owners risk owing even more if rates stay high.
Distress Watch: Bisnow reports that strong top-tier malls are masking deep trouble underneath, with Green Street finding mall values up 13% but most of that gain concentrated in Class-A malls while hundreds of others struggle. Bisnow